The question
Does a market-guided gating layer still improve predictions of US stock returns once trading costs are counted?
The method
I ported the MASTER transformer to US stocks using free data only: prices from yfinance and company filings from SEC XBRL, matched to the date each filing was public. I removed the market-guided gating step and compared results with and without it, charging trading costs in every test. The comparison was repeated across many random starting points and again with five times the training budget. A Barra-style factor model shows which sources of risk drive the returns.
Tools and methods
The evidence
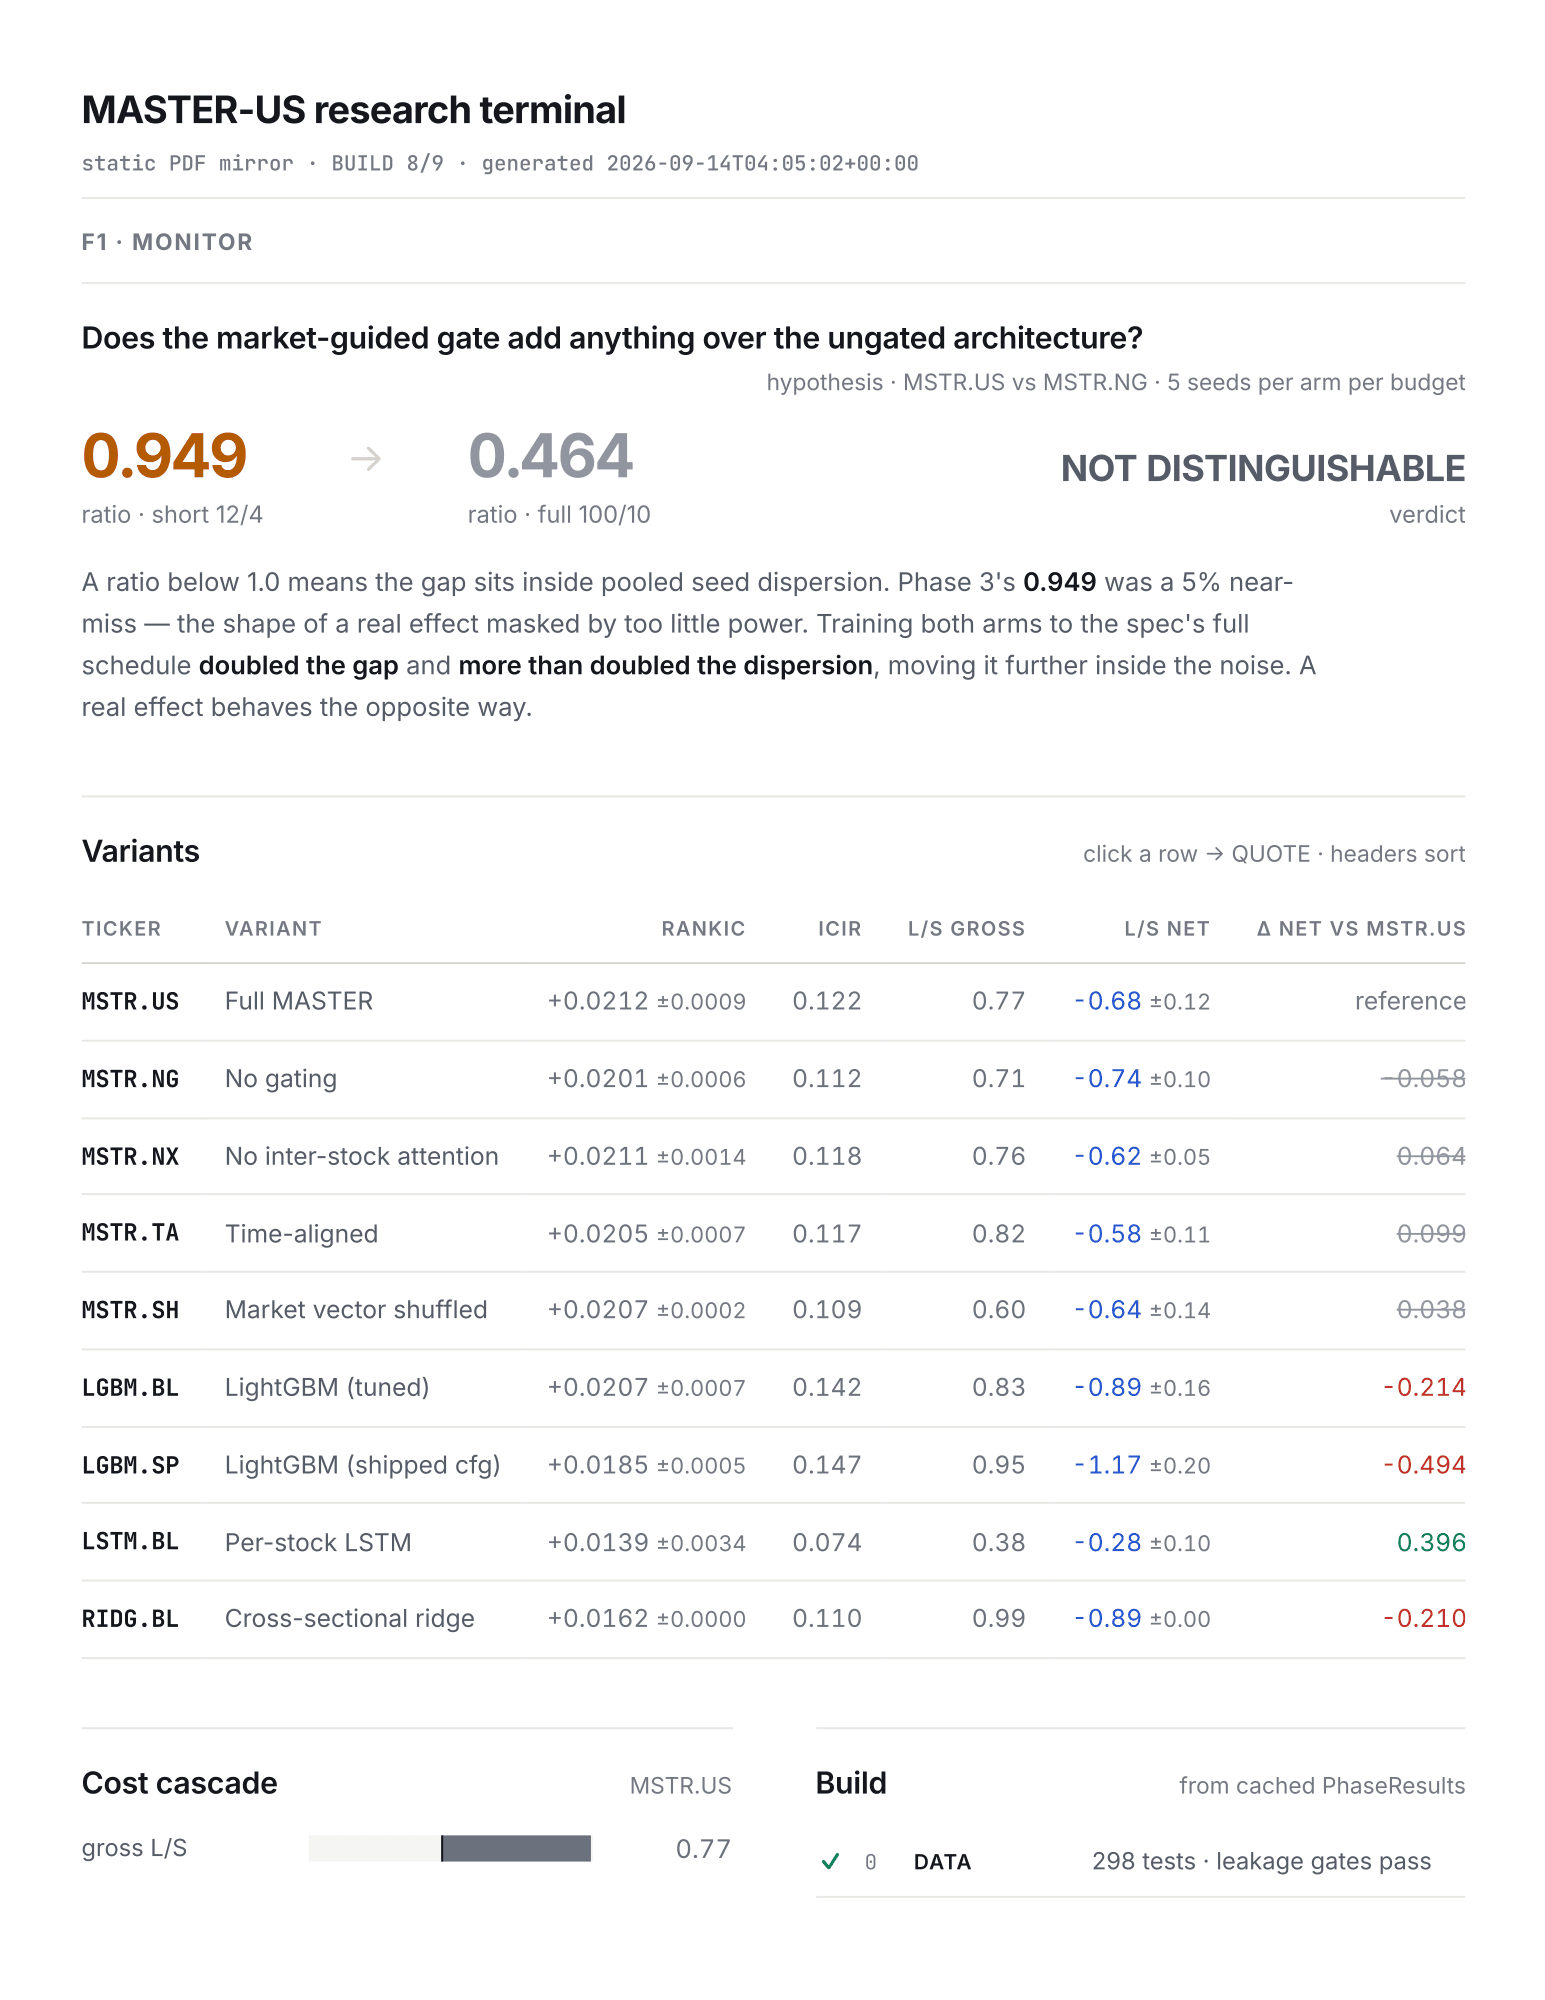 Open MASTER-US terminal (PDF)
Limits
The original authors' validation and test splits cannot be reproduced, so this work is a port to the US market and not an exact replication. A risk-adjusted return of 1.28 for the part of the signal left after removing known factors assumes hedging is free, so it should not be quoted as a result.